The Building Itself
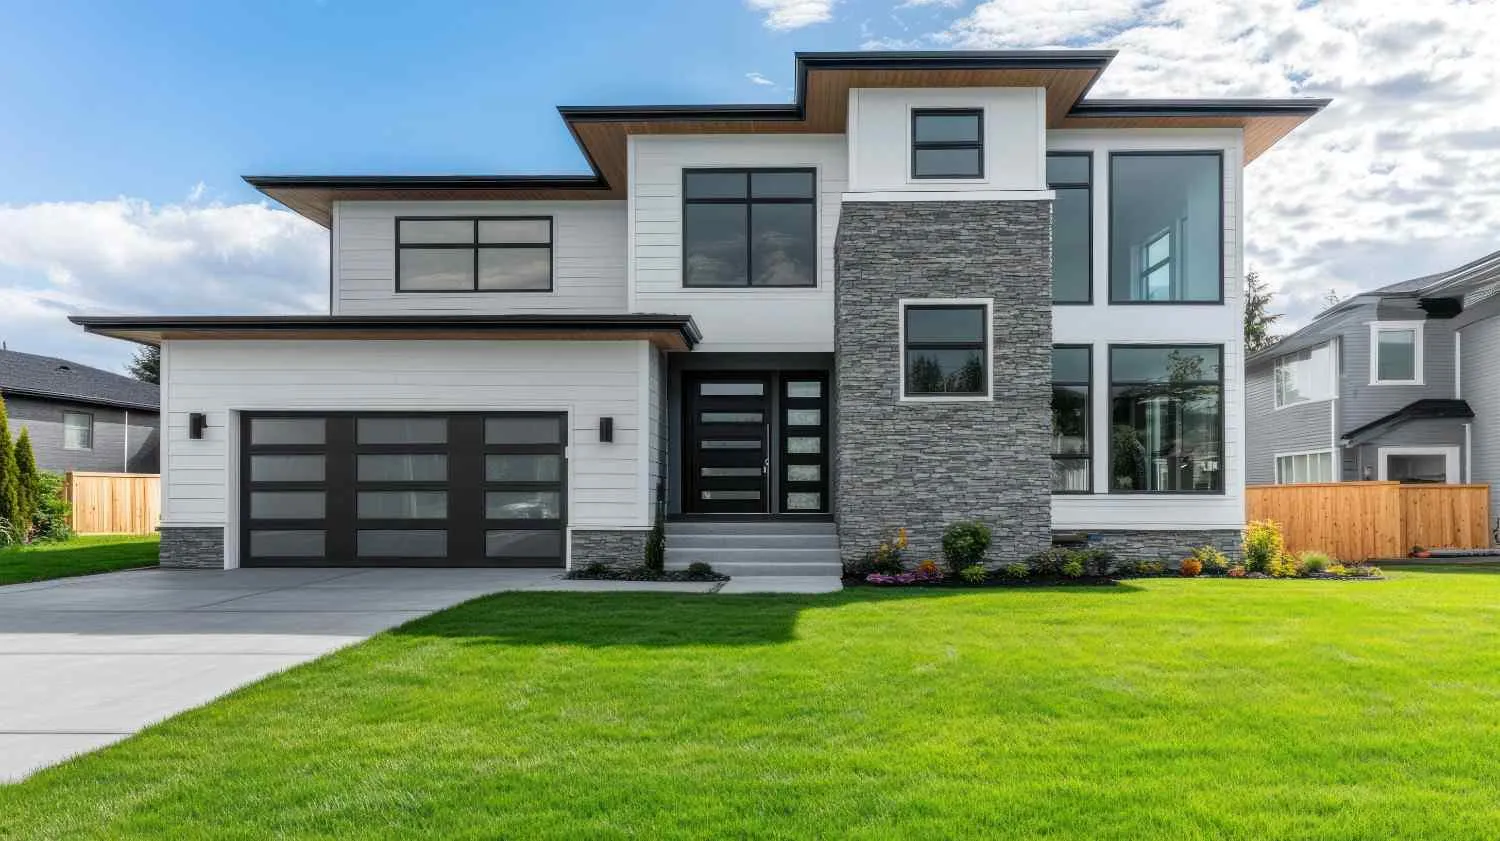
Walls, roof, floors and the attached garage. I make sure a repair or a full rebuild is paid for after fire, hail or water.
Read More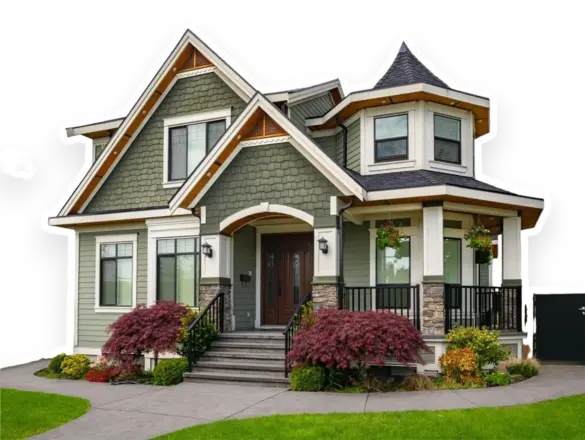
Your house keeps you warm, dry and safe all year. I set up the cover that pays your house back when a storm, a leak or a burglary lands on it, and a free quote from me takes only a few minutes.
Get A Free QuoteNo two houses are alike. A tired cottage still running its first set of wiring needs cover that a fresh build with a finished basement never will, so I start your quote at your roof, your rooms and your budget rather than a number pulled off a form.
Walls, roof, floors and the attached garage. I make sure a repair or a full rebuild is paid for after fire, hail or water.
Read More
Furniture, clothes, kitchen gear and gadgets. I set limits that genuinely refill a room after a theft or a soaking.
Read More
Guest injuries, dog bites and rent while repairs run. I make sure the bills after an accident land on the policy.
Read More
Ask me what a deductible truly costs after a hailstorm and I give you the figure, not a brochure line.
I write the policy and I work the claim, so you never describe your house to a stranger twice.
I flag tired roofs, detached garages and home offices while there is still time to sort them.
Most of mine come back the same day. Send me your address, the age of the roof and a rough idea of what your belongings are worth, and I can have real numbers with you inside a few hours.
A standard home policy leaves out rising water from a storm or a creek that jumps its banks. That takes a separate flood policy, and I tell you up front instead of letting you learn it when a claim is refused.
A newer roof, a monitored alarm, fresh wiring, a higher deductible and putting more than one policy in the same place all pull the number down. Ask me and I will write you a list built on your house, not a generic one.
Yes. Most carriers hand back the unused part of what you already paid. I set the start date on the new policy so no gap ever opens between the old cover and the new one.
They usually do. A finished basement, a fresh deck or a gutted kitchen lifts the cost to rebuild, so your limits need to climb with it. Message me once the work is done and I will keep everything lined up.