Home Coverage
What a home policy protects, what usually sits outside it, and the extras I tell people to ask about before signing.
Three Parts To Every Home Policy
Home insurance really has only three moving parts: the structure, the belongings inside it and the costs that follow an accident. I walk you through all three first, because knowing which one pays saves a fight later when it counts.
Walls, Roof And Everything Attached
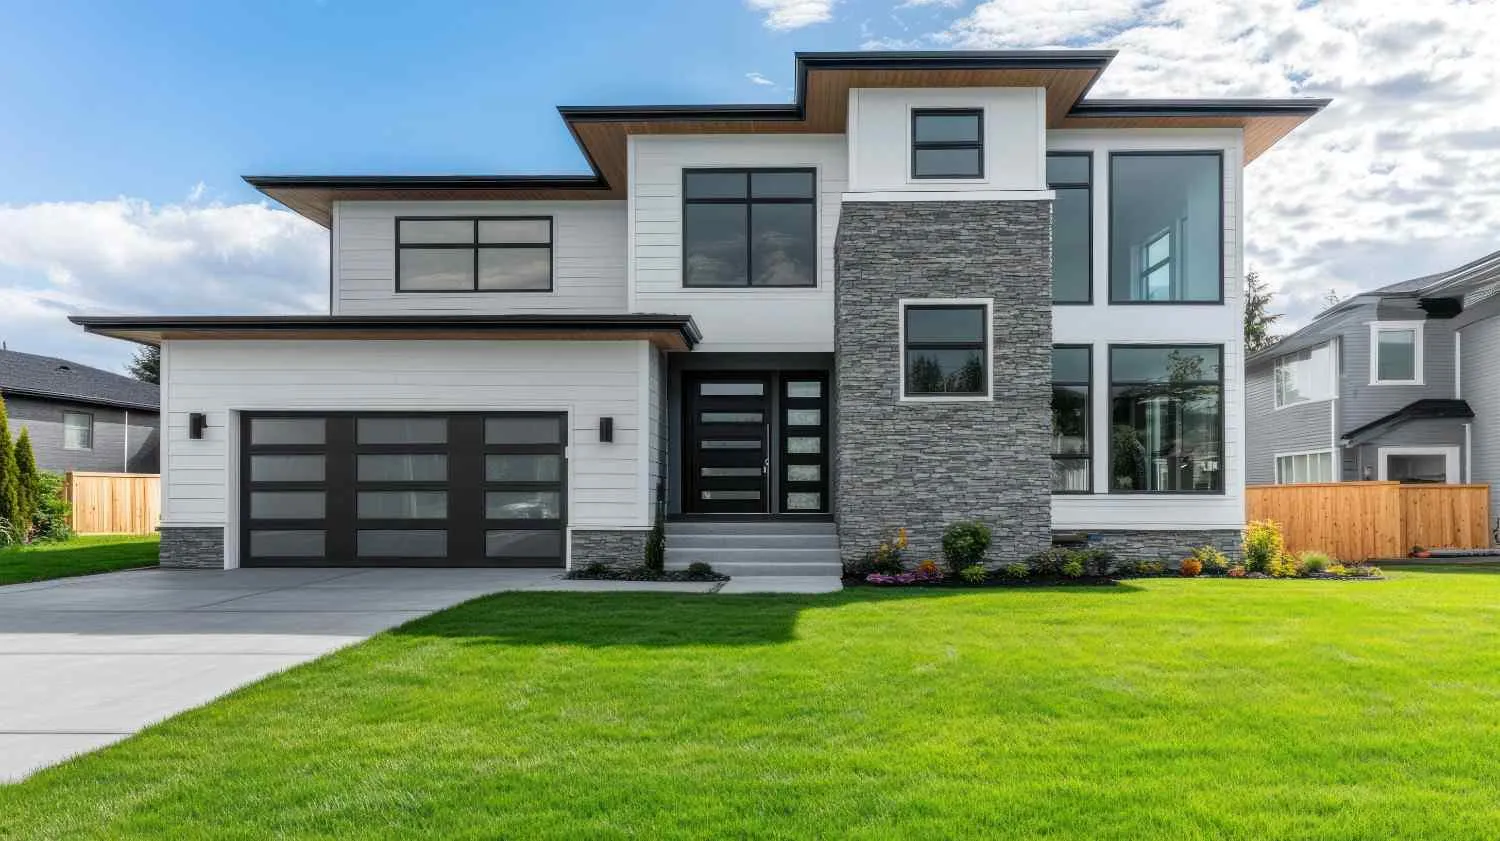
This is the part that puts the house back up. I price it against what building would truly cost today rather than what the place might sell for, and it takes in anything bolted, framed or plumbed into the structure.
- Roof, walls, floors, foundation and attached garage
- Built in cabinets, fixed appliances, furnace and water heater
- Fire, hail, wind, falling trees and sudden water damage
- Fences, sheds and detached structures on request
The Contents That Make It A Home
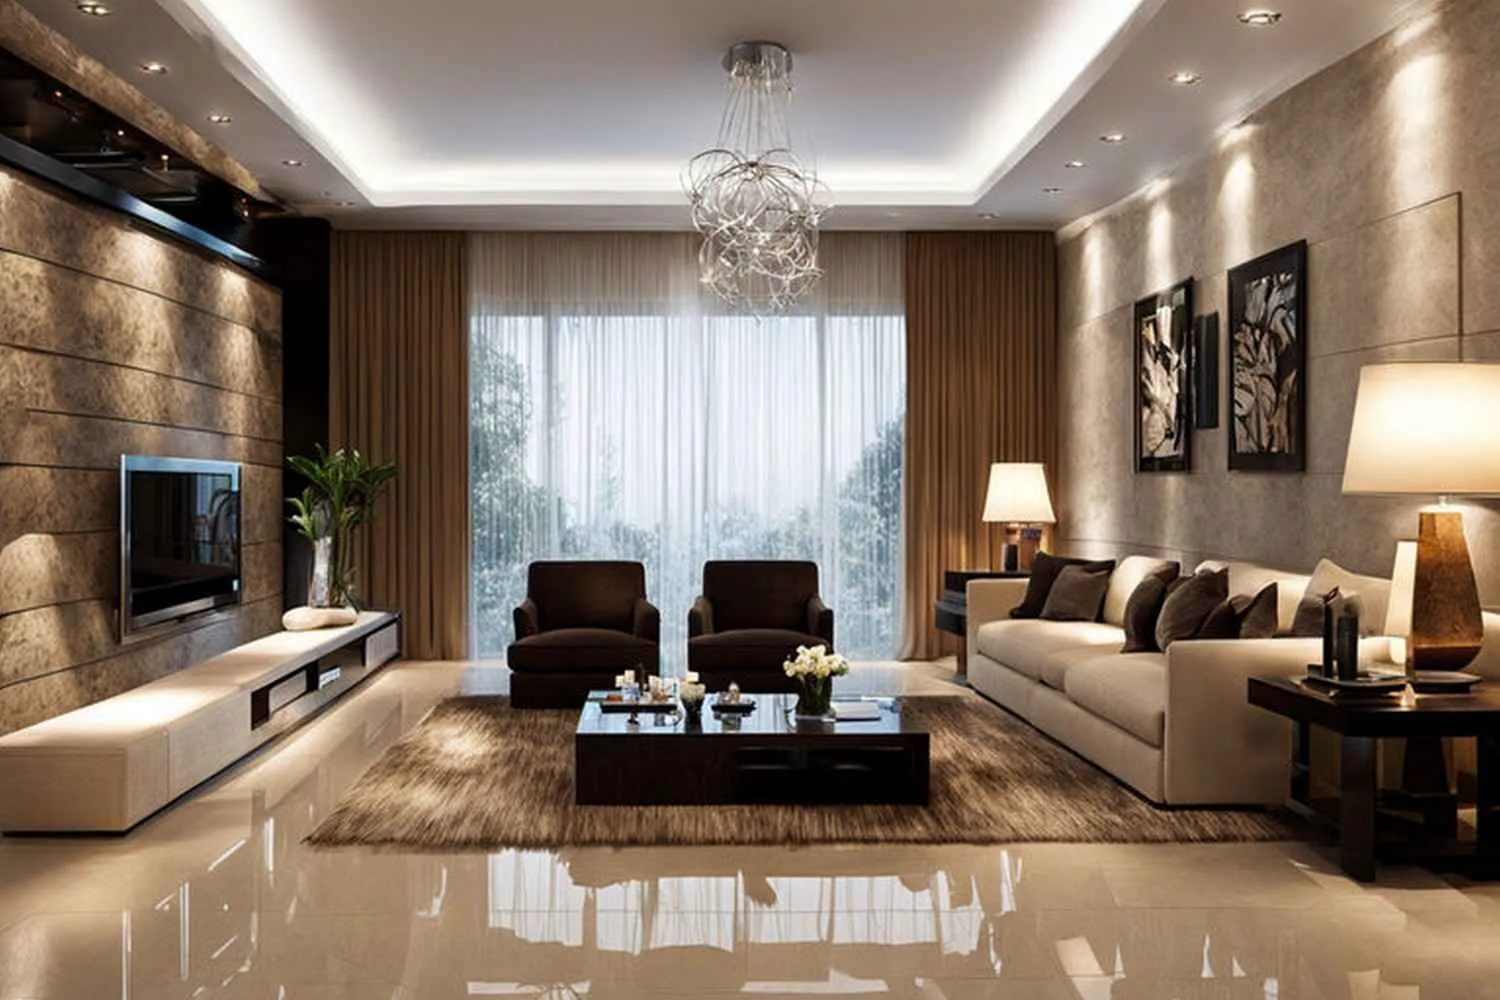
Everything that would fall out if you turned the house upside down. Contents cover replaces what theft, fire or water took, and I set the limit after walking your rooms rather than rounding to a tidy figure.
- Furniture, clothing, kitchen equipment and electronics
- Tools, bicycles and gear kept in the garage or shed
- Items taken outside the home such as a laptop on a trip
- Replacement cost wording so age does not shrink the payout
The Costs That Follow An Accident
The quiet part of the policy nobody reads until the day it matters. Liability steps in when another person is hurt or their property is wrecked, and additional living expenses keep your household fed and housed while the place is rebuilt.
- Guest injuries on the property and the legal costs behind them
- Damage done to a neighbor by something starting at the house
- Hotel, rental and meal costs while repairs are under way
- Medical payments for minor injuries without a dispute
Usually Sitting Outside A Standard Policy
Rising Water And Flooding
Water arriving from a river, a storm surge or a saturated street needs its own flood policy. A standard home policy will not answer for it, and I would far rather you hear that from me now than from an adjuster later.
Earth Movement
Earthquakes, sinkholes and general shifting ground are excluded almost everywhere. Separate cover exists, and I will price it for you if the ground around your place has a habit of moving.
Wear, Rot And Pests
Insurance answers for sudden and accidental damage. A roof that quietly wore out, timber gone soft with rot or a termite trail all land under maintenance, which sits with you rather than the policy.
Sewer Or Drain Backup
Water pushing back up through a basement drain is a separate endorsement on most policies. It costs very little to add, and it is the surprise I watch catch homeowners more than any other.
Business Property At Home
Stock, client equipment and a serious home office setup usually sit above the standard limit. A small endorsement or a separate business policy closes that gap, and I will tell you which one fits.
High Value Individual Items
Rings, watches, instruments and collections sit under a category cap far lower than most people expect. Schedule them separately and I can put their genuine value on the policy.
Extras Worth Asking About
Scheduled Valuables
Names one item at an agreed value, so a lost ring pays what it is genuinely worth instead of striking the blanket jewelry cap buried in the policy.
Water Backup Endorsement
Handles the cleanup bill and the ruined contents when a sump pump quits and water climbs back into your lowest floor.
Extended Replacement Cost
Adds a cushion above your rebuild limit for the stretches when materials and labor cost far more than they did at renewal.
Ordinance Or Law Cover
Pays the extra it takes to rebuild to codes in force today, which matters most on older homes that would never be permitted the way they were first built.
Service Line Cover
Handles the buried water, sewer and power lines running from the street to your door, which almost always belong to you rather than the utility.
Identity Fraud Support
Covers the paperwork, the filing costs and the recovery help after somebody takes your personal details and uses them where they never belonged.